Did Trump Lift Sanctions on Russia? No — But California’s Refinery Closures Raise a Bigger Diesel Question
Official Treasury and White House documents show that U.S. sanctions remain in effect. Meanwhile, California has lost 17% of its refining capacity through two major refinery closures. Could America’s shrinking domestic fuel-processing capacity help explain Washington’s temporary authorization of Russian diesel transactions?
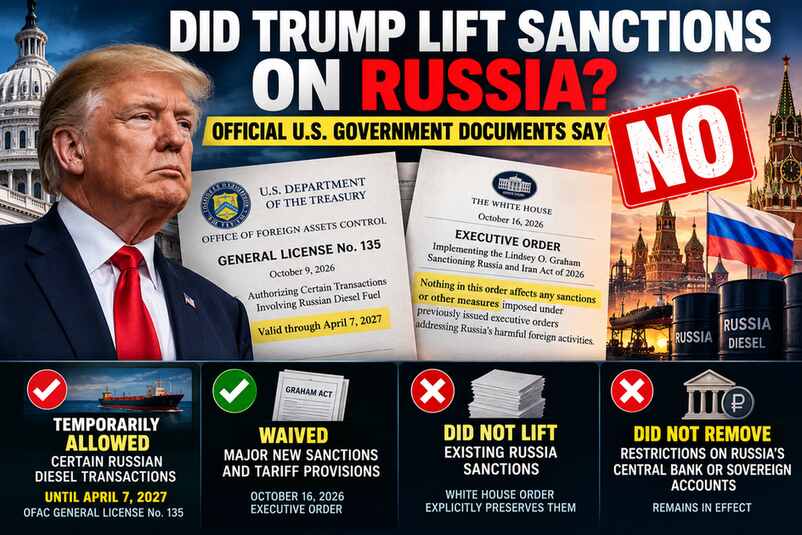
WASHINGTON, October 18, 2026 — President Donald Trump did not eliminate existing U.S. sanctions against Russia.
On October 9, 2026, the U.S. Treasury Department’s Office of Foreign Assets Control (OFAC) issued General License No. 135, temporarily authorizing certain transactions involving Russian-origin diesel fuel until April 7, 2027.
The official license permits specified commercial transactions without terminating the broader sanctions regime against Russia.
On October 16, Trump also signed an executive order implementing the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026. The order waived major new sanctions and tariff provisions while explicitly preserving existing restrictions imposed under earlier presidential authorities.
These were targeted authorizations and statutory waivers — not the wholesale cancellation of sanctions against Russia.
But an equally important economic question deserves investigation: Why was Washington opening additional channels for diesel transactions while California was losing major domestic refining capacity?
California Lost 17% of Its Refining Capacity
The U.S. Energy Information Administration (EIA) reported on July 9, 2025, that two planned refinery closures would eliminate approximately 17% of California’s crude-oil refining capacity.
The affected facilities were:
- Phillips 66 Los Angeles-area refinery: approximately 139,000 barrels of crude-oil processing capacity per day, with refining operations scheduled to end in 2025.
- Valero Benicia refinery: approximately 145,000 barrels per day, with the company announcing plans to idle, restructure, or cease refining by April 2026.
Together, those facilities represented approximately 284,000 barrels of crude-oil processing capacity per day.
According to EIA, the two refineries accounted for about 17% of California’s refining capacity, 11% of West Coast capacity, and less than 2% of total U.S. capacity.
Although neither refinery was individually the largest in California, their combined closure represents a substantial reduction in the state’s fuel-production infrastructure.
The federal agency warned that the closures could increase fuel-price volatility because California has limited pipeline connections to major refining centers elsewhere in the United States.
EIA also identified Asia as a likely source of replacement petroleum products, particularly gasoline and jet fuel.
Source: EIA — Refinery Closures Present Risk for Higher Gasoline Prices on the West Coast.
Why Did Phillips 66 and Valero Decide to Close?
The decisions occurred during Democratic Governor Gavin Newsom’s administration, which has maintained extensive environmental and climate-related regulation of petroleum refining.
However, the companies’ published explanations must be distinguished from political interpretations of those decisions.
Phillips 66: Long-Term Sustainability and Market Conditions
On October 16, 2024, Phillips 66 announced plans to cease refining operations at its Los Angeles-area facility in the fourth quarter of 2025.
Chairman and CEO Mark Lashier attributed the decision to uncertainty about the refinery’s long-term sustainability and changing market dynamics.
The announcement also identified the approximately 600 employees and 300 contractors operating the facility at the time.
Phillips 66 stated that it would continue supplying the California market through other sources, including its refining network and alternative fuel facilities.
The company’s announcement did not identify a particular California law as the sole reason for closure.
Valero: Refinery Shutdown Plans and a $1.1 Billion Charge
On April 16, 2025, Valero Energy announced that it had notified the California Energy Commission of plans to idle, restructure, or cease refining operations at Benicia by the end of April 2026.
Valero also disclosed a $1.1 billion combined pre-tax impairment charge associated with its Benicia and Wilmington facilities.
Its regulatory disclosures identified legal, political, and regulatory developments, along with market conditions and operating expenses, as business risks.
The announcement did not quantify how much any specific California regulation contributed to the decision.
The distinction matters: California’s regulatory environment is economically relevant, but the published company statements do not establish that Governor Newsom personally ordered the refineries closed.
How Much Potential Diesel Production Was Lost?
A refinery’s crude-oil processing capacity is not equivalent to its diesel output.
Refineries convert crude oil into several products, including gasoline, diesel, jet fuel, and other petroleum products.
Nevertheless, the scale of the lost processing capacity allows an illustrative comparison.
If the two facilities operated continuously at their rated capacities, their combined annual crude-oil processing potential would be approximately:
284,000 barrels per day × 365 days = 103.7 million barrels of crude oil per year.
The EIA’s refinery-yield data provide a basis for estimating how much distillate fuel might be produced from that volume.
Using an illustrative distillate yield of 30%, the lost annual production potential would be approximately:
103.7 million × 30% = 31.1 million barrels of distillate fuel per year.
Distillate fuel oil includes diesel and related products. This estimate is not a measurement of the two California refineries’ actual historical diesel output.
It also assumes full utilization of their processing capacity.
The figure therefore represents a scenario for potential annual production, not a verified decline in U.S. diesel production.
The Cumulative Loss Through October 2026
The timing of the closures is essential.
Phillips 66 ended refining operations in 2025, while Valero planned to cease operations by April 2026.
Using approximately one year of downtime for Phillips 66 and 170 days for Valero, the potential loss of crude-oil processing capacity through October 17, 2026, can be estimated as follows:
| Refinery | Assumed downtime | Potential crude processing not performed |
|---|---|---|
| Phillips 66 Los Angeles | 365 days | 50.7 million barrels |
| Valero Benicia | 170 days | 24.7 million barrels |
| Combined | 75.4 million barrels |
Applying the same illustrative 30% distillate yield produces approximately 22.6 million barrels of cumulative potential distillate output.
This calculation is a capacity-based scenario rather than an estimate derived from refinery-specific production records.
It does not account for historical operating rates, changes in product yields, or replacement output from other facilities.
Most importantly, it should not be interpreted as 22.6 million barrels of proven net lost U.S. diesel supply.
How Does That Compare With Russian Diesel?
In October 2026, Trump’s administration authorized certain transactions involving Russian-origin diesel through OFAC General License No. 135.
Public discussion surrounding the decision has included proposed shipment volumes of hundreds of thousands of metric tons.
For comparison, 300,000 metric tons of diesel would equal approximately 2.24 million barrels, using an approximate conversion of 7.46 barrels per metric ton.
A hypothetical expanded supply schedule totaling 4.8 million metric tons would equal approximately 35.8 million barrels.
| Volume compared | Approximate barrels |
|---|---|
| Illustrative initial Russian diesel shipment of 300,000 metric tons | 2.24 million |
| Illustrative cumulative distillate potential lost in California through October 17 | 22.6 million |
| Hypothetical expanded Russian diesel schedule of 4.8 million metric tons | 35.8 million |
| Annual distillate potential of both California refineries at full utilization | 31.1 million |
The comparison is significant in scale, but the numbers describe different things.
The Russian quantities are shipment scenarios, not actual deliveries verified by Treasury. The California figures describe potential production capacity, not measured diesel output.
Furthermore, the OFAC license does not specify a purchase volume, identify a U.S. government procurement contract, or guarantee that Russian diesel will enter the American market in those quantities.
The documents therefore do not prove that California’s refinery closures caused Trump’s decision to authorize Russian diesel transactions.
They do establish that Washington was seeking flexibility over diesel supply at a time when California had been losing a significant amount of refining capacity.
Why Is California Increasing Its Dependence on Imported Fuel?
California has an unusual fuel-supply system.
Unlike much of the United States, the West Coast is poorly connected by petroleum-product pipelines to the major refining centers of the Gulf Coast.
The state also requires specially formulated gasoline to comply with its air-quality standards.
As EIA explained in its July 2025 assessment, these conditions make it difficult to replace lost local production rapidly with supplies from other U.S. refineries.
Instead, replacement shipments may arrive by sea from overseas suppliers, including facilities in Asia.
The agency warned that longer ocean transportation routes increase the time needed to respond to unexpected shortages.
That creates potential exposure to delayed deliveries, higher logistics costs, and price volatility.
The issue is not that importing petroleum products is inherently uneconomic. It is whether the cost of replacing nearby domestic production with more distant supplies is adequately reflected in California’s energy planning.
Newsom’s Administration Acknowledged the Import Strategy
In a January 6, 2026 statement, Governor Newsom’s office discussed Valero’s plan to continue supplying Northern California using inventories and imported fuel after idling the Benicia refinery.
The administration emphasized its cooperation with the company and efforts to maintain stable supplies.
This confirms that imported finished fuel was part of the replacement strategy.
It does not, by itself, establish the additional cost of those imports or their eventual effect on retail prices.
What Do California Consumers Pay?
California drivers pay fuel taxes and face regulatory costs that differ from those in many other states.
The state’s gasoline and diesel prices reflect multiple components, including crude-oil costs, refining margins, distribution, retail expenses, taxes, and environmental compliance.
The California Energy Commission’s gasoline price breakdown identifies these components and publishes estimates of how they contribute to retail prices.
Meanwhile, the California Department of Tax and Fee Administration publishes the applicable state fuel-excise tax rates.
Programs such as the Low Carbon Fuel Standard and emissions-trading requirements can also affect the cost of supplying transportation fuels.
Those costs must be evaluated alongside the environmental benefits the programs are intended to deliver.
There is, however, an important limitation: the complete difference between California fuel prices and the national average cannot be attributed to the two refinery closures.
Oil prices, California’s fuel specifications, transportation constraints, taxes, market competition, refinery outages, and other factors all influence the final retail price.
A precise consumer-loss estimate would require a defensible counterfactual: what prices would have been if both refineries had continued operating under otherwise comparable market conditions?
No such definitive calculation is established by the documents reviewed for this article.
Did California’s Climate Policies Play a Role?
California has pursued policies designed to reduce transportation-related greenhouse gas emissions and promote lower-carbon fuels.
Those policies may change the expected long-term profitability of conventional petroleum refining.
Companies deciding whether to invest hundreds of Millions of Dollars in aging facilities must consider projected fuel demand, operating costs, environmental compliance, and possible future restrictions.
Both Phillips 66 and Valero identified economic uncertainty in connection with their California operations.
Valero additionally identified regulatory developments among its business risks.
Nevertheless, claiming that the companies closed solely because of Democratic climate regulations would go beyond the published evidence.
Similarly, attributing the closures entirely to changing market conditions without considering regulatory costs would provide an incomplete economic analysis.
The relevant investigation should determine the actual weight of each factor.
Did Trump Remove Russia Sanctions? What the Law Actually Says
The controversy over Russian diesel should not obscure the legal facts.
October 9: Temporary OFAC Authorization
The Treasury Department issued General License No. 135, permitting specified Russian diesel transactions until April 7, 2027.
The authorization does not lift all Russian sanctions and does not generally permit debits to blocked accounts belonging to Russia’s Central Bank, National Wealth Fund, or Ministry of Finance.
October 16: Waivers Under the Graham Act
Trump then signed the executive order implementing the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026.
The order invoked presidential authority to waive new sanctions and additional tariffs provided by the legislation.
But Section 4(b) explicitly preserved sanctions imposed under earlier executive orders addressing harmful foreign activities by the Russian government.
The Treasury Department’s Russia sanctions program remains operative.
The administration therefore made two distinct policy decisions: permitting certain fuel transactions temporarily and waiving major portions of a newly enacted sanctions statute.
Neither decision amounted to the complete termination of the existing Russian sanctions regime.
Five Questions California Officials Should Answer
The official record leaves several important questions unresolved:
- How many barrels of conventional diesel did the Phillips 66 Los Angeles and Valero Benicia refineries actually produce during their final full operating years?
- How much additional finished diesel, gasoline, and jet fuel has California imported specifically to replace the two facilities’ output?
- What additional costs have import dependence and longer transportation routes imposed on California distributors and consumers?
- What portion of the companies’ decisions was attributable to state regulations, compliance costs, expected fuel demand, or other market factors?
- Has the state published a comprehensive cost-benefit assessment comparing the economic effects of losing domestic refinery capacity with the environmental objectives of its policies?
Answers would allow the public to distinguish measurable economic consequences from political accusations.
Conclusion: Sanctions Remain, but the Refinery Question Is Unresolved
The official record establishes three central facts.
First, President Donald Trump did not repeal the existing U.S. sanctions regime against Russia. Treasury issued a limited diesel authorization, and the White House separately waived substantial new sanctions and tariffs under the Graham Act.
Second, California lost approximately 17% of its refinery processing capacity through the planned closures of Phillips 66 Los Angeles and Valero Benicia. The federal EIA warned that this could increase dependence on imported products and heighten West Coast fuel-price volatility.
Third, the potential amount of distillate production associated with the closed facilities is economically significant, but it must not be confused with measured diesel shortages or confirmed Russian imports.
Whether California’s regulatory framework materially contributed to the closures, and whether those closures influenced Washington’s diesel policy, remain separate questions requiring additional evidence.
The next stage of the investigation should focus on actual refinery diesel-production records, replacement imports, and the economic costs borne by California consumers.
Official and Primary Sources
- U.S. Treasury — Issuance of Russia-Related General License No. 135, October 9, 2026
- OFAC — General License No. 135, Full Text (PDF)
- White House — Implementing the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026
- OFAC — Russian Harmful Foreign Activities Sanctions
- EIA — Refinery Closures Present Risk for Higher Gasoline Prices on the West Coast
- EIA — U.S. Refinery Yield Statistics
- Phillips 66 — Official Los Angeles Refinery Closure Announcement, October 16, 2024
- Valero — Official Benicia Refinery Announcement, April 16, 2025
- Governor of California — Statement on Valero Benicia, January 6, 2026
- California Energy Commission — Gasoline Price Breakdown and Margins
- California Department of Tax and Fee Administration — Fuel Tax Rates
Midtown Tribune | Independent analysis based on U.S. government documents, federal energy statistics, and official corporate disclosures.
Midtown Tribune Independent USA news from New York
Ask Midtown Tribune about this story
Answers are grounded first in this article. Search all Midtown Tribune reporting from the main AI Search page.
AI-generated summary. Verify important details in the linked original articles.